
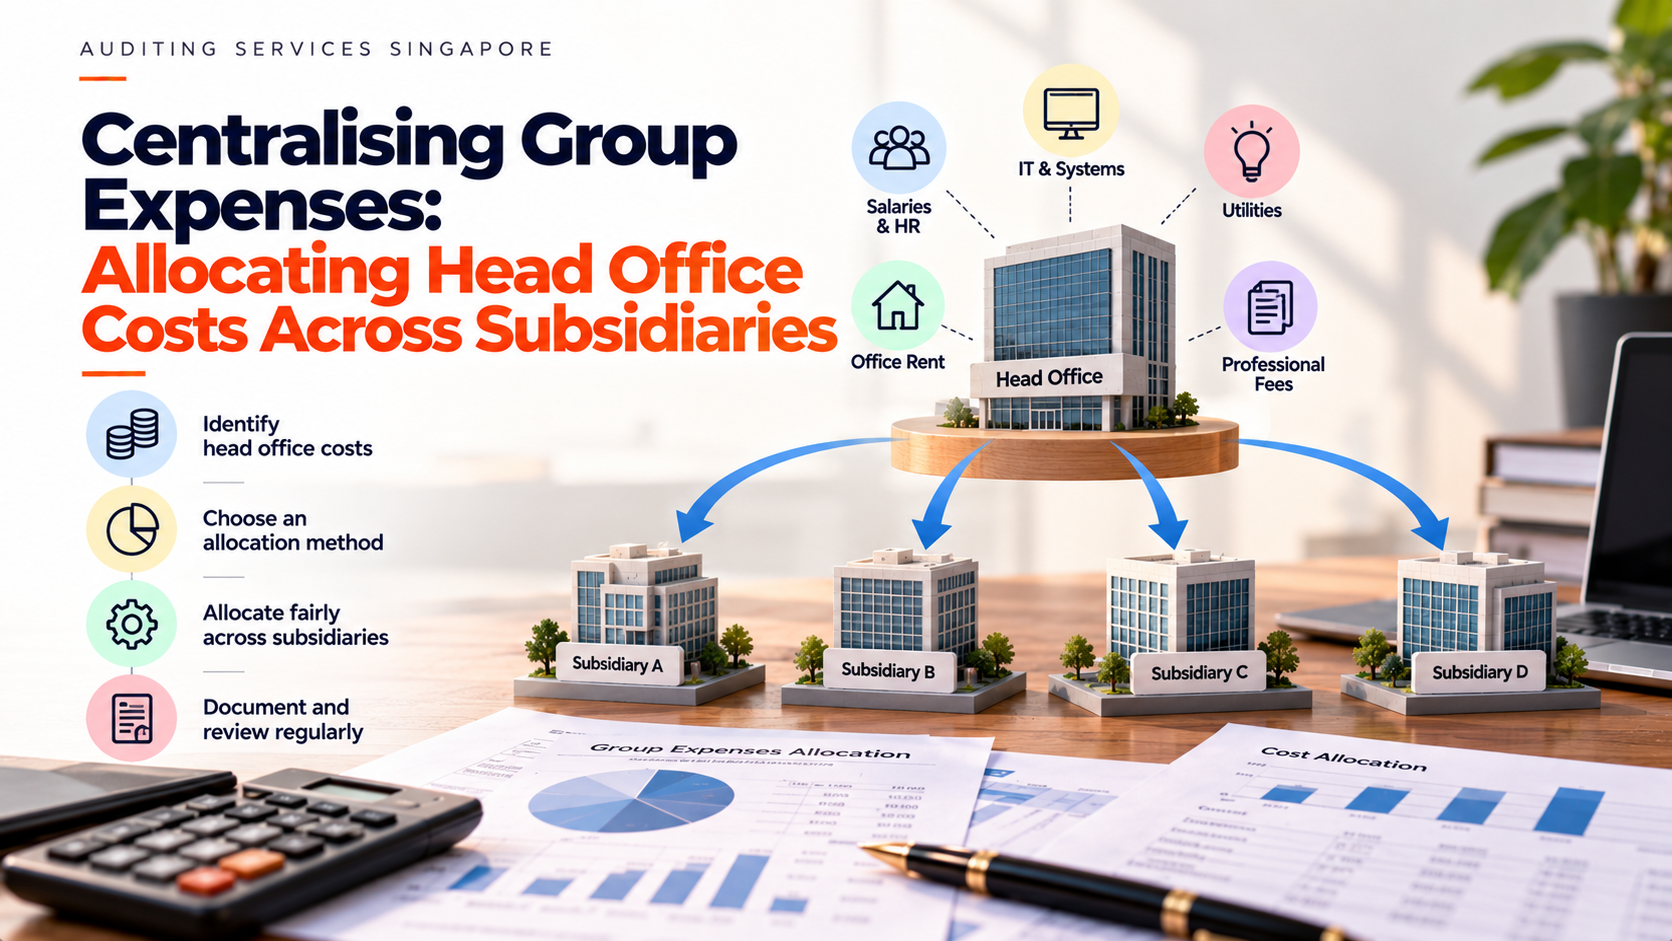
A growing group often brings finance, human resources, technology and administrative support into a central team. Subsidiaries gain access to shared resources, while head office coordinates systems and processes across the business. The operational case may be clear, but the financial reporting becomes more complicated when those costs need to be allocated.
One subsidiary questions why its charge increased despite receiving the same support. Another argues that revenue is an unsuitable basis because it has relatively few employees. Head office wants to recover its expenditure, but the allocation is becoming a source of disagreement rather than useful management information.
Lee & Hew provides accounting, consolidation and tax services and identifies holding companies and groups among its areas of focus. For businesses centralising expenses, a workable approach starts with understanding the services provided, identifying the beneficiaries and selecting a supportable charging method. Dividing the head office budget between subsidiaries is only the arithmetic at the end of that process.
Clarify the Purpose of the Allocation
Groups allocate costs for different reasons. Management may want to understand the full cost of operating each business, prepare subsidiary budgets or establish charges between separate legal entities. These objectives are connected, but they are not identical.
An internal management report might distribute corporate overhead to help directors compare business units. An intercompany invoice creates an amount receivable by one entity and payable by another, with accounting and potentially tax consequences.
Before choosing a formula, establish what the exercise is intended to achieve. Identify whether the output will be a management reporting allocation, an actual service charge or both. Where the same information serves several purposes, explain any adjustments needed between them.
This distinction prevents an internal budgeting convention from becoming an intercompany charging policy without further review. A useful management measure still needs to be assessed before it is used to determine amounts charged between entities.
Identify the Services Behind the Cost
“Head office expenses” is too broad a description to support a meaningful allocation. It could include payroll processing, IT support, recruitment, treasury activities, management oversight and costs incurred solely for the parent company.
Break the expenditure into identifiable activities. For each activity, describe what the central team does, which entities receive support and how that support is evidenced.
A finance team might process supplier invoices for three subsidiaries but prepare management reports for five. An IT team may maintain systems used throughout the group while completing a separate implementation project for one entity. Treating all that activity as one service can obscure significant differences.
The description does not need to record every minor task. It should be detailed enough for a subsidiary manager to understand what the proposed charge relates to and for finance to identify an appropriate allocation basis.
Distinguish Shared Services From Parent-Only Activities
A cost incurred at head office is not automatically a service provided to every subsidiary. Some activities are undertaken because the parent owns investments or has its own obligations.
IRAS’ transfer pricing guidance distinguishes shareholder activities from services that benefit other group members. Costs arising solely from the parent’s ownership role do not justify a service charge merely because subsidiaries belong to the group.
Management should therefore review the cost pool before allocating it. Where employees perform both parent-related work and services for subsidiaries, the analysis should distinguish those activities on a reasonable, supported basis.
This review also helps identify potential duplication. If a subsidiary already performs an activity locally, head office should explain what additional service it provides. Similar job titles do not necessarily mean the work is duplicated, but an overlapping responsibility deserves examination before a charge is applied.
Assign Directly Identifiable Costs First
Some expenditure can be attributed to a particular subsidiary without using a group-wide formula. A recruitment assignment for one entity, a dedicated software licence or a clearly identified project may have a direct connection to its recipient.
Separating these items reduces the amount that must be allocated indirectly. It also prevents other subsidiaries from absorbing costs associated with work they did not receive.
For example, a head office team may spend several months helping one subsidiary introduce a new inventory system. If that project is included in a general administrative pool, every subsidiary could receive part of the charge despite the work having a specific beneficiary.
Keep the underlying records and assess the appropriate charging treatment. Direct identification answers who the activity relates to; it does not, by itself, determine every accounting or pricing question. The remaining genuinely shared expenditure can then be considered separately.
Choose a Basis That Reflects the Service
Different services may require different allocation methods. Headcount could be relevant to some employee support activities, while software users may provide a more useful basis for certain technology costs. Processing volumes or recorded effort may be relevant to other services.
Revenue can be appropriate in some circumstances, but it should not be selected simply because it is readily available. A high-revenue subsidiary may require little administrative support, while a smaller business may generate many transactions or employee queries.
The method should have a reasonable connection to the expected benefit or use of the service. It should also rely on information that the group can maintain consistently.
Avoid creating an unnecessarily elaborate system. A method that requires extensive data nobody can collect reliably may be less useful than a simpler, well-supported approach. The choice should balance relevance, reliability and practicality, with its limitations understood.
Understand How the Method Changes the Result
Consider a hypothetical group with three subsidiaries and an eligible annual payroll support cost pool of S$120,000. Assume that the services are comparable across employees and that average employee numbers provide a reasonable allocation basis.
Subsidiary A has 60 employees, Subsidiary B has 30 and Subsidiary C has 10. On that basis, the allocated costs would be S$72,000, S$36,000 and S$12,000 respectively. These figures illustrate cost allocation before considering any applicable mark-up or taxes.
Now suppose the same entities generate 20%, 30% and 50% of group revenue. A revenue-based allocation would produce charges of S$24,000, S$36,000 and S$60,000. Subsidiary C would bear half the cost despite having one-tenth of the employees.
The example does not establish headcount as the correct basis for every payroll arrangement. It shows why management should examine the connection between the service and the chosen measure. Differences in processing complexity could require a more refined approach.
Define Which Costs Enter the Pool
Even a reasonable allocation method can produce an unreliable result if the underlying cost pool is incomplete or contains unrelated expenditure. Define which categories belong to each service and reconcile the amounts with the accounting records.
Relevant expenditure might include employee costs, systems and other resources used in delivering the activity. The treatment of mixed-use resources needs a documented basis.
Review unusual items separately. A major restructuring project, an acquisition-related assignment or a one-off system conversion may not belong in the same recurring pool as ordinary support. The beneficiary and nature of the activity should guide the assessment.
The group should also avoid counting the same expenditure twice. A directly charged project should not remain in the shared pool unless the calculation clearly removes the amount already attributed. A reconciliation between total expenditure, excluded items, direct charges and shared costs makes the calculation easier to review.
Assess Pricing Separately From Allocation
An allocation formula explains how a cost pool is distributed. It does not automatically establish the appropriate price for a transaction between related parties.
IRAS requires related-party services to be priced on an arm’s length basis. Its acceptance of a cost-plus-5% approach applies to specified routine support services where the stated conditions are met. It is not a universal mark-up for every head office activity.
The group should assess the nature of the service, the relevant pricing requirements and the supporting documentation. Cross-border arrangements also need consideration of the recipient jurisdiction’s requirements.
Lee & Hew’s service offering includes accounting and transfer pricing work. Groups reviewing central charges can discuss how the operational allocation connects with their reporting and tax obligations. Management should establish that connection before treating a convenient allocation calculation as a complete charging policy.
Document the Arrangement Before Billing
Subsidiaries should understand the service and charging basis before receiving a large year-end invoice. A documented arrangement can describe the scope of support, the cost basis, the allocation method, billing frequency and review process.
It should also explain how significant changes will be handled. A new subsidiary may join partway through the year, an entity may stop using a service, or a major project may require a separate agreement.
The supporting calculation should be understandable without relying on the person who prepared it. Retain the source data, relevant dates and explanation of adjustments.
Documentation works best when it reflects the actual arrangement. A general agreement covering “management services” is of limited help if nobody can identify the work performed or explain how the charge was calculated. The records and operational practice should tell the same story.
Use Provisional Charges With a Clear Adjustment Process
A group may use budgeted costs for regular billing because final expenditure is not yet available. That can support timely reporting, provided the arrangement explains how provisional amounts will be reviewed and adjusted.
Compare the budgeted pool with actual expenditure and investigate significant differences. Distinguish higher service costs from changes in the allocation data or the scope of work.
For example, a subsidiary’s charge could increase because the central team became more expensive, because the subsidiary added employees or because it began receiving additional services. Each cause has a different implication for management.
Where the policy requires a final adjustment, calculate it transparently and communicate it early. An unexpected year-end charge can distort subsidiary forecasts and create disputes, particularly if local management had no visibility of the developing difference.
Present Subsidiary Performance With Context
Allocated expenses can materially change how a subsidiary’s results appear. Directors may find it useful to review performance before and after central charges, with a clear explanation of what each measure shows.
The before-charge view can help assess local operating performance, while the after-charge view shows the effect of the allocated support. Neither should be presented as the only relevant measure without context.
Managers should also be able to distinguish costs they control from charges determined centrally. This does not remove their responsibility to use shared resources efficiently, but it helps make performance discussions more meaningful.
A subsidiary appearing less profitable after a policy change may not have become operationally weaker. The change could reflect a more complete allocation, a revised method or increased head office spending. Reporting should explain which factors drove the movement.
Keep Entity Records and Group Reporting Connected
Once charges are issued, both entities need enough information to record them consistently. Invoice references, service periods and calculation schedules help prevent the receiving company from treating the charge as an unexplained balance.
Reconcile the related receivable and payable and investigate differences before group reporting. A subsidiary’s disagreement should be resolved through the appropriate review process rather than left for the consolidation team to absorb.
In consolidated reporting, relevant intragroup charges are eliminated. That does not remove the underlying external expenditure incurred by the group, and allocating it differently does not by itself reduce the group’s total costs.
Lee & Hew’s accounting and consolidation services are relevant to maintaining this connection between entity records and group reports. Clear supporting schedules make it easier to distinguish genuine cost changes from the effects of internal charging.
Review the Policy as the Group Changes
An allocation method can become less representative as subsidiaries grow, systems change or services become centralised. Review the policy when there are significant operational changes, as well as at the planned review date.
Ask whether the beneficiaries remain the same, whether the cost pool still reflects the service and whether the allocation data remains reliable. Keep a record of changes and their rationale so that comparisons between periods remain understandable.
Lee & Hew provides services across accounting, consolidation and tax, supporting discussions about the different implications of group expense arrangements. For directors, the useful starting point is a clear description of the work performed and the entities that benefit.
A defensible allocation policy makes head office charges explainable. It allows subsidiaries to understand what they are paying for, gives management a clearer view of performance and provides a consistent basis for recording and reviewing the arrangement.